The Timeline of a Forex Scam: What Happens Between Hello and the Second Payment
A forex scam is a sequence, not a single lie, and each step is designed to make the next one feel normal.
Updated Oct 2026 · how we rate brokers
It Starts With a Message You Did Not Ask For
The first contact rarely mentions forex. It is a wrong-number message, a social media follow, a group chat invite, or someone who saw your profile and thinks you would be good at this. The tone is friendly and the ask is small: just a reply.
Within a day or two the conversation moves to a trading platform. Screenshots appear showing winning positions, usually timed to London or New York hours, which in the UAE run 12:00 to 21:00 and 16:00 to 01:00 GST. That timing is deliberate: it matches when you are free to look at your phone.
Nothing has been requested yet. The scammer is building a habit, not a transaction. Your job at this stage is simply to notice that an unsolicited message about money is a sales pitch, whoever it appears to come from.
| Part of the day | Local time · GST |
|---|---|
| Busiest window | 16:00-21:00 GST — London and New York open together |
| Thinnest stretch | 01:00-10:00 GST — Sydney alone, wider spreads |
| European open | 12:00-21:00 GST |
| US open | 16:00-01:00 GST |
| Closed | Friday New York close until the Sydney open on Monday |
The hours are shown for the clocks in force today: GMT for London until 28 March, EDT for New York until 1 November. The UAE does not change clocks, so each move shifts these local times by an hour and the page is rebuilt on the day it happens.
The Platform Looks Real Because It Is Designed To
You are given a link to a site with live prices, a clean dashboard and a support chat that answers quickly. Prices on these sites often mirror real market data, which makes the whole thing feel legitimate. A working chart proves nothing about who holds your money.
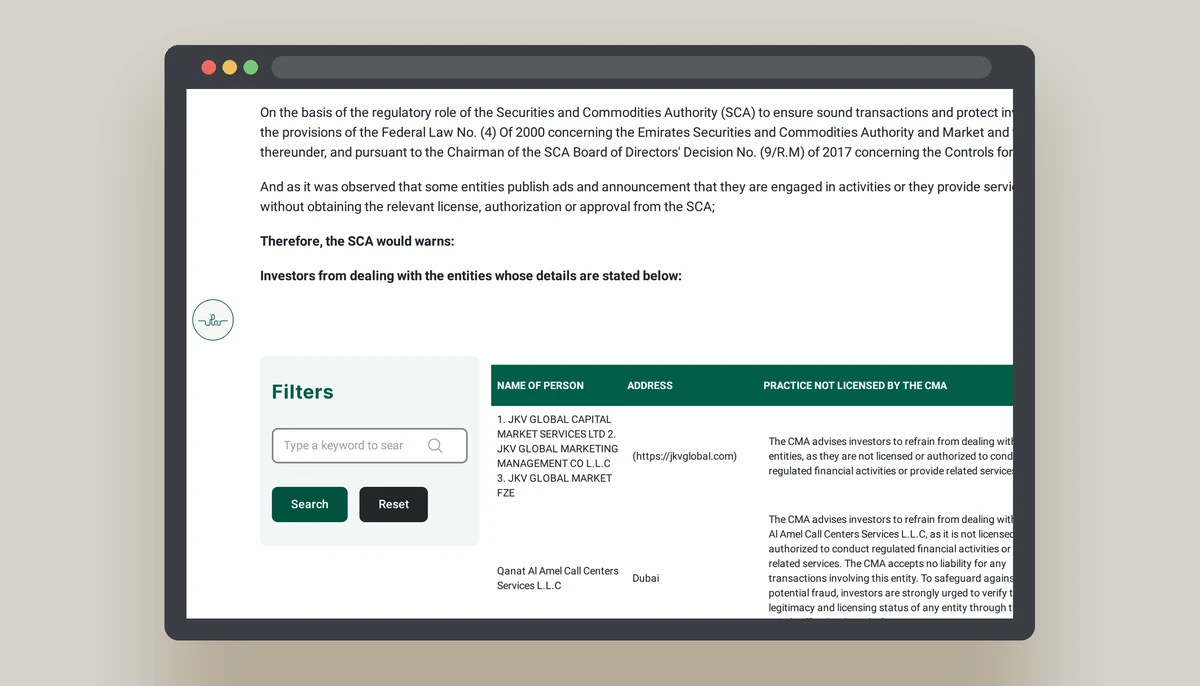
The test that matters is not the website. It is whether the firm appears on the CMA register of licensed companies at uaecma.gov.ae. If it does not, the dashboard is decoration. Note also which regime a licence sits under, because the Capital Market Authority onshore, the DFSA in the DIFC and the FSRA in the ADGM each handle complaints differently.
This is the moment to slow down. You have not lost anything yet, and a register check takes less time than the chat conversation you have already had.
| Platform | What it is | Who makes it |
|---|---|---|
| MetaTrader 4 | The older standard; expert advisors and a large script ecosystem | MetaQuotes |
| MetaTrader 5 | The newer build; more order types and timeframes | MetaQuotes |
| cTrader | Depth of market and a different order model | Spotware |
| The broker's own app | Usually simpler, and tied to that one firm | The broker |
A platform is software, not a safeguard: the same terminal is offered by licensed and unlicensed firms alike. A high rating is not a permission. The register is where the licence is confirmed.
The First Deposit Is Small and the First Withdrawal Is Easy
You are encouraged to start small, and the platform makes funding simple: bank transfer, local bank transfer, card or international wire. The amount is not the point. The point is getting a payment instruction from you into their system.
Then something unusual happens. You ask to withdraw a small sum and it arrives, sometimes quickly. That single success does more damage than any chart. It converts a stranger's website into something you now trust with larger sums.
Treat an easy first withdrawal as a sales technique, not evidence. A firm willing to return a small amount to collect a large one is running a cost, not a favour.
How deposits and withdrawals travel
- Local bank transfer
- Limits set by your bank and the broker
- Card
- Card payment — limits set by your card issuer and the broker
- International wire
- Bank transfer — limits set by your bank and the broker
Limits and fees are set by the provider and the broker and change without notice, so they are not printed here. Read the limits in the provider's app, then on the broker's funding page, and keep the payout route the same as the deposit route.
Then the Requests Change Shape
The withdrawal that worked before now needs a fee, a tax payment or a verification deposit before it can be released. The account manager becomes harder to reach, or a new person appears with a different explanation. Each request is framed as the last obstacle.
This is the step the whole sequence was built for. Money already sent is used as leverage: you are told that paying once more releases everything. In practice, the requests continue for as long as you keep answering.
Two habits protect you here. First, check any platform against the CMA register before funding, not after a problem appears. Second, decide in advance what you will do when a withdrawal is blocked, because that decision is much harder to make while you are still hoping.
| Figure | Value | Source |
|---|---|---|
| Indicative USD/AED | 3.67 | open.er-api.com, pulled 2026-09-28 |
| How often it moves | Every trading day | — |
| The rate your account uses | Your broker's own conversion | The broker's rate card |
| Symbol on this site | AED | — |
An indicative rate is for sizing a position in your head, not for settling one. Your broker's conversion will not match this rate, and that difference is a real cost.
The Message Arrives on Gulf Time, and That Is Part of the Design
A first contact often lands in the evening, after the working day, when replies feel casual and unhurried. In the UAE the sender may be several hours behind or ahead, so the conversation stretches across your sleep. Treat the timing itself as information: a stranger who is always available at midnight GST is not a busy licensed desk.
Real firms operate on published hours. A registered entity has a compliance function, a switchboard and staff who keep a normal schedule. When every message arrives within minutes at any hour, including Friday, the responsiveness is a sales operation rather than client service. Save the timestamps and note the pattern.
The practical consequence is that you cannot judge urgency by your own clock alone. Set a rule before you reply: no funding decision is made in the same session as the first message. Wait until the next UAE business day, then check the CMA register at uaecma.gov.ae while you are calm and the pressure has faded.
The register, in brief
- Regulator
- Capital Market Authority (CMA)
- Register
- CMA register of licensed companies
- Published at
- uaecma.gov.ae
- Covers retail forex
- Yes — the register has a category for it
- Last read by us
- 2026-09-29
- Entries transcribed here
- 27
A register says whether a firm holds a licence on the day you look, and nothing about how it treats clients. Use the company name from the site's footer - that is what a register will know it as.
A Small First Withdrawal Is a Test of Your Patience, Not Proof of Honesty
The early withdrawal is designed to buy trust cheaply. It usually arrives, and it usually arrives quickly, because the operator needs you to tell yourself the account is genuine. What the page has not covered is the order of operations after that: the second deposit is the one that matters, and it is requested before any larger withdrawal is tested.
Readers get this backwards. They treat the first successful withdrawal as evidence and then relax the checks they would normally apply. The correct sequence is to verify the licence and legal name first, before any money moves, and to treat every withdrawal as untested until a large one clears through the same route it was funded by.
If a platform allows a small withdrawal but changes the method, the bank details or the stated processing time for a larger one, that shift is the signal. Compare what the broker's own funding page says with what the bank transfer app shows you. Where they disagree, stop and ask the question in writing.
| Figure | Source | Checked |
|---|---|---|
| Licensee names and status | CMA register of licensed companies — uaecma.gov.ae | 2026-09-29 |
| Session windows | Fixed UTC windows; London and New York shift in their DST | On change |
| USD/AED | open.er-api.com | 2026-09-28 |
| Funding limits and fees | Set by the provider and the broker — not published here | Changes without notice |
A figure with no source and no date is a guess with good manners. Anything we could not trace is left out rather than printed from memory.
Bank Transfer Leaves a Trail, but the Trail Is Only Useful If You Keep It
Most UAE residents fund by bank transfer, and that is the rail with the clearest record. The advantage is not automatic. It exists only if the payment reference, the beneficiary name and the account details are saved and matched to the platform you thought you were paying. Screenshot the confirmation before the app clears the screen.
A common failure is paying a beneficiary whose name differs from the trading name on the homepage. That difference is exactly what a later complaint or police report will turn on. Check the legal name against the CMA register at uaecma.gov.ae, and if the bank shows a different recipient, treat that as a stop signal rather than a detail.
Card and international wire each behave differently when something goes wrong, and crypto generally cannot be recalled. The order of operations is to decide the funding rail before you open the account, keep every reference, and never move a second payment to a new beneficiary on the strength of a chat message alone.
| Document | What it proves |
|---|---|
| Emirates ID or passport with residence visa | Who you are |
| Selfie with the ID document | That the document is in your hands |
Brokers usually also ask for proof of address - Ejari or utility bill; requirements differ per firm. What a particular firm will take is written on its own account-opening page.
After the Loss, the Calendar Matters More Than the Argument
Once a withdrawal is blocked, the useful work is administrative and time-bound. Report to your bank while the transfer is still traceable, keep the reference, and record dates in GST so the sequence is unambiguous. The longer the gap between payment and report, the less any rail can do for you.
Do not spend that time arguing with the platform. Replies are designed to keep you engaged and to delay the moment you contact the bank or the authorities. A message asking for more money to release a withdrawal is not a negotiation, it is the same request in a new shape, and answering it costs you days you cannot recover.
Write down what happened in order: first contact, first deposit, first withdrawal, the change in requests, the block. That single timeline is what a bank, the CMA or the police will ask for. Keep it factual, keep the screenshots, and do not accept a recovery offer that arrives unprompted after the loss.
Four claims worth one minute of checking
- A fixed monthly return, promised in advance
- Ask which licence permits it, then look the firm up on the CMA register of licensed companies.
- A deposit asked for in gift cards or vouchers
- Check the broker's own funding page: firms list bank, card and wallet rails, not vouchers.
- Someone offering to trade the account for you
- Managing money for a client is a separate permission. The register says whether a firm holds it.
- A withdrawal released only after a new payment
- Read the withdrawal terms you agreed to. Such a fee, if invented at payout, is not part of them.
None of this is a judgement about any firm. Each line is a check you can run yourself, starting at uaecma.gov.ae.
How quickly can a fake trading platform take my money?
The pattern usually runs over days or weeks rather than hours. Contact, a small deposit, an easy first withdrawal, then a blocked withdrawal with a new fee attached. The delay is intentional: it gives you time to build trust, and it gives the scammer time to keep asking.
Should I move my trading to a platform that accepts crypto?
Payment method is not a safety signal. Crypto transfers are fast and hard to reverse, which suits a scammer, but a bank transfer to an unlicensed firm has the same end result. Check the firm on the CMA register at uaecma.gov.ae first, then look at the funding page and decide from there.
What should I do if a withdrawal is already blocked?
Stop sending money. A request for an additional fee or tax to release funds is the classic escalation, and paying it does not unlock anything. Keep the chat logs and payment records, contact your bank about the transfer, and report the matter. If the firm claims a licence, check which regulator it names and approach that regulator directly.
First time doing this?
Learn what paying in and out looks like in the UAE first - it is a short read and it answers most of it.